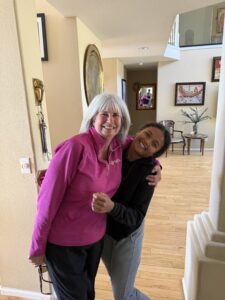What benefits🎁 are you leaving on the table🤔🍽️❓

July Greetings … may this blog find you in amazing health, with your Medicare health insurance working well and no one on this planet killing you with kindness.

Do you or your friends need help with their Medicare options🤔?

Email Gray@TheBig65.com or book a time on my calendar because referrals truly are the lifeblood of my business. Plus we’ll send you a Starbucks card for anyone who books an appointment☕🎁💳.

Twenty three years after our first exchange student, Romain and his wife Christine sent their first born to spend a few weeks with us in Colorado. I can’t believe how fast time flies!

Karl Bruns-Kyler and a young man looking at the camera.

Of course we’re having great fun with Justin:

  • Exploring the National parks
  • Paddle boarding
  • Playing soccer⚽
  • Riding bikes
  • Watching World Cup games (and seeing ALL my teams lose😢)
  • Sleeping late
    x

How many chances do we get to spoil the people we love? It’s a privilege, isn’t it?

A montage of photos of Karl and Justin doing different activities in Colorado.

The bottom line is we only live once so let’s not leave anything on the table, right?

Which brings us to the midway point in July and many of you are leaving Medicare benefits on the table, benefits that might make you healthier and happier!

And for those concerned about my wife Quantz, she survived her attempt to run with the bulls🐂 in Pamplona, Spain😮‍💨. Now she’s home safe and sound.

But let’s get back to the benefits!

Quantz taking a selfie in Spain for the Running of the Bulls.

Got a sore body part? If you have a Medicare Supplement, ask your doctor about physical therapy, even if you haven’t had surgery.

Medicare Part B covers medically necessary outpatient physical therapy to:

  • Restore movement following an injury, illness or surgery
  • Improve strength, balance or mobility
  • Maintain a person’s current abilities
  • Slow physical decline
    x

A physician or other qualified provider must certify the need, but there is no annual dollar limit on medically necessary outpatient therapy.

Sadly, the Japanese beetles have been providing no therapy for our roses!

Close-up photo of a rose with a Japanese beetle.

Consider asking your primary physician the following questions:

  • Am I due for my Annual Wellness Visit?
  • Am I current on Medicare-covered screenings and vaccines?
  • Would physical therapy help with my strength, balance, pain or mobility?
  • Do I qualify for nutrition, diabetes or weight-management counseling?
  • Could I qualify for home health care while recovering from an illness or surgery?
    x

If you’re unsure what might be helpful, call the member services number on the back of you Medicare Supplement card. Do take advantage of your benefits.

In our neighborhood, we have a momma bear and her cub taking advantage of the trash cans!

That’s my gate bent in backwards. Thank goodness this bear didn’t get into my backyard or my bees would have been their dessert!

Karl backyard door and also a separate picture of a bear on top of a fence.

Now if you have a Medicare Advantage plan, it may include hundreds—or even thousands—of dollars in additional benefits. But if you don’t know how to access them, those benefits may expire without ever being used.

Plan benefits vary considerably by plan and county, so look at your summary of benefits (or call the carrier for a copy) and check for:

  • Dental cleanings, X-rays and allowances
  • Routine vision exams and eyewear
  • Hearing exams and hearing-aid benefits
  • Over-the-counter product allowances
  • Fitness memberships
  • Transportation to medical appointments
  • Post-hospital meals
  • Personal emergency-response systems
  • In-home support services
  • Flex-card balances and quarterly allowances
    x

Every plan is different but there is usually something helpful in every plan.

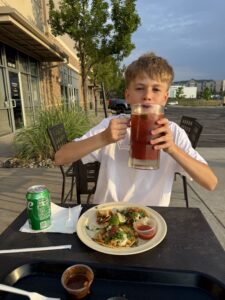
Was it not helpful to teach Justin to like Micheladas (Mexican tomato beers)😉🤠?

Justin drinking from an oversized beer glass.

Whether you have Medicare Supplement or Medicare Advantage coverage, no plan is perfect.

Understand the coverage you have, leverage the benefits that will make you better, and then get out there and live this summer, cause life is shorter than you think!

Karl Bruns-Kyler of The Big 65 Medicare Insurance Services.

Keep asking,  “What’s the next big thing?”

If family or friends need help… referrals are the lifeblood of my business.

If you know someone who might like to receive The Big 65 newsletter, forward this link.

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@theBig65.com.

Let us know what’s going on and please send pictures :).


Karl Bruns-Kyler

(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in over thirty states from around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Kentucky
Louisiana
Maryland
Michigan
Mississippi
Missouri
Montana
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
South Dakota
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Karl Bruns-Kyler of The Big 65 Medicare Insurance Services.

🤖 AI doesn’t know everything!

Spring Greetings … may this blog find you smiling, with your Medicare insurance coverage keeping you in the pink.

Wondering about Medicare Supplements or Medicare Advantage plans or the meaning of life?  Email Gray@TheBig65.com or book a time on my calendar and we’ll do our best to help.

Special thanks to Quantz’s childhood friend, Elaine, for taking care of our exchange student, Miti, while we were on the road.

Elaine and Miti hugging each other.

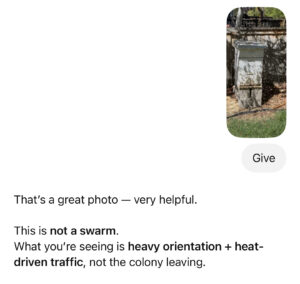
A few days after returning home, one of my hives looked like it was starting swarm.

Since I couldn’t get in touch with my bee mentor, I took a picture of the hive. Here’s what ChatGPT said:

Screenshot of ChatGPT response to swarm question.

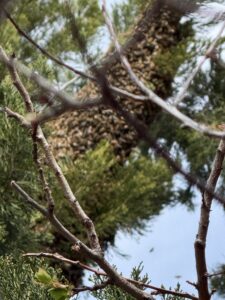
I was greatly relieved by the response and started back into the house when I heard a very loud buzzing up in the trees.

A bunch of bees up in a tree.

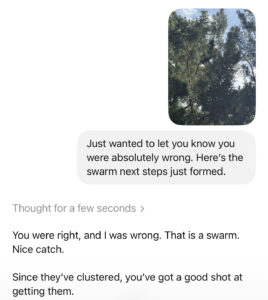
Of course I knew the answer but I decided to ask one more time and here was the response.

Screenshot of bee swarm in tree and follow-up response form ChatGPT.

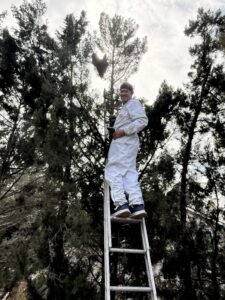
The good news was that I was able to capture the runaway Queen and her 20,000 swarmers. You can see the capture if you click on the picture below.

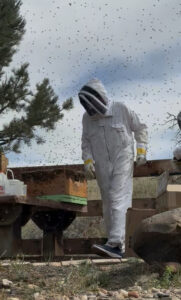
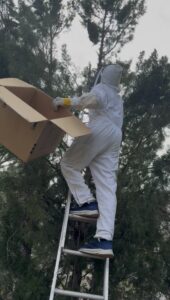
Karl in a white bee suit standing on a ladder.

The bigger lesson is a very helpful reminder that my technologist daughter reminds me of frequently:

AI is a great predictive tool designed to please you, not a definitive source of accurate answers. Let the user beware.

Tools like Claude, ChatGPT, Gemini, and others can be remarkably helpful for seniors when used the right way.

Karl in a white bee suit surrounded by flying honey bees.

They can simplify confusing topics, help write emails, organize travel plans, summarize articles, generate healthy meal ideas, and explain complicated information on Medicare topics in plain English.

Karl in a white bee-keepers suit.

But like any powerful tool, they work best when used with a little caution: never share private financial or medical information, always double-check important facts, and remember that AI should support your judgment, not replace it.

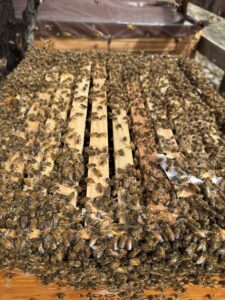
A close-up photograph of honey bees.

With the help of my beekeeping mentor, we captured the swarm and the queen and set up two new hives at my buddy Joe’s house.

Joe is one of those people who never stops learning. He’s excited to be a newly minted beekeeper but smart enough to have already signed up for an in person beekeeping class.

Plus, he’ll use AI to augment his knowledge about the art of beekeeping and also to have fun. Isn’t this a great meme he created?

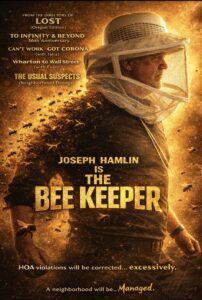
A beekeeper meme created by ChatGPT.

For the past eight years, every week, I sit down and personally write this weekly newsletter. But I leverage AI for summaries, suggestions, and to find source material.

AI is tool, but it only works well when you provide very specific prompts. Here is a link to a three minute video on how create helpful prompts.

Since my wife Q is still in Sicily visiting our Airman and his girlfriend for a couple more days, I make this prompt simple:

Quantz, please come home, we miss you!

The Big 65 Medicare Insurance Brokers.

To summarize best practices:

  • Use AI like a helpful assistant, not the final word.
  • Never enter private medical, financial, or personal information.
  • Let it help you get organized and make confusing things easier to understand.
  • Use it to brainstorm and think more clearly, but keep your own judgment switched on.
  • Be cautious with medical, legal, and financial advice.
  • AI can sound polished and confident even when it is flat wrong.
  • The clearer your question, the better the result.
  • AI is a tool to help you, not a relationship to replace people.

Used correctly, AI can be an amazing helper. Just remember, don’t surrender your judgement, your privacy, or your common sense or you’ll end up on a ladder chasing bees!

Karl in a white beekeeping suit, standing on a ladder.

Keep asking,  “What’s the next big thing?”

If family or friends need help… referrals are the lifeblood of my business.

If you know someone who might like to receive The Big 65 newsletter, forward this link.

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@theBig65.com.

Let us know what’s going on and please send pictures :).


Karl Bruns-Kyler
(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in thirty states around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Kentucky
Louisiana
Maryland
Michigan
Minnesota
Missouri
Montana
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Karl Bruns-Kyler of The Big 65 Medicare Insurance Services.

7 Reasons Why Medicare Advantage Plans Are Bad (Or are they?)

If you’ve been researching Medicare, you’ve probably heard friends, family, or even doctors say that Medicare Advantage plans are bad. With over 33 million Americans enrolled in these plans, opinions run strong on both sides.

Schedule a Free Medicare Coverage Review

The truth? Medicare Advantage plans aren’t inherently bad, but they’re not right for everyone. The real problem is that many people enroll without fully understanding the trade-offs. After 20 years of helping Medicare beneficiaries navigate their options, I’ve seen firsthand when these plans work well and when they create serious frustration.

Let’s take an honest, balanced look at the common complaints about Medicare Advantage, the legitimate advantages, and how to decide which path is right for you.

What Is a Medicare Advantage Plan?

Before diving into the criticisms, it helps to understand what Medicare Advantage actually is. Medicare Advantage (Part C) plans are offered by private insurance companies approved by Medicare. They bundle Part A (hospital), Part B (medical), and usually Part D (prescription drugs) into a single plan.

These plans are required to cover everything Original Medicare covers, but they can add extra benefits like dental, vision, hearing, and fitness programs. In exchange, enrollees typically agree to use a network of providers and follow the plan’s rules for referrals and prior authorization.

7 Common Complaints About Medicare Advantage Plans

These are the most frequent issues Medicare beneficiaries report. Each one is legitimate and worth understanding before you enroll.

1. Restrictive Provider Networks

This is the number one complaint. Unlike Original Medicare, where you can see any doctor or hospital that accepts Medicare anywhere in the country, Medicare Advantage plans limit you to a specific network of providers.

With HMO plans, you must use in-network providers except in emergencies. PPO plans offer some out-of-network coverage, but at significantly higher costs. If your preferred doctor, specialist, or hospital isn’t in your plan’s network, you may need to switch providers or pay the full cost out of pocket.

This is especially problematic for:

  • Snowbirds who split time between states
  • People with established specialist relationships for chronic conditions
  • Rural residents with fewer in-network options nearby

2. Prior Authorization Delays

Prior authorization is a process where your insurance company must approve certain treatments, tests, or procedures before they’re performed. While Original Medicare rarely requires prior authorization, Medicare Advantage plans use it extensively.

According to the Kaiser Family Foundation, over 2 million prior authorization requests were fully or partially denied by Medicare Advantage insurers in recent years. Even when authorizations are approved, the process can delay care by days or weeks while paperwork is processed.

For someone waiting on an MRI, a specialist referral, or a surgical procedure, these delays can feel agonizing, and in some cases, they can impact health outcomes.

3. The “Nickel-and-Dime” Cost Structure

Many Medicare Advantage plans advertise $0 monthly premiums, which sounds incredible. But the real costs show up as you use your healthcare:

  • $10-$50 copays for primary care and specialist visits
  • $100-$300 copays for imaging (MRIs, CT scans)
  • Daily hospital copays that can reach $350+ per day
  • Coinsurance percentages for certain services

These expenses add up quickly, especially if you have chronic conditions or need frequent medical care. The maximum out-of-pocket limit for Medicare Advantage plans can be as high as $9,250 in 2026 for in-network services. For someone on a fixed income, that’s a significant financial burden during a health crisis.

4. Annual Plan Changes

Medicare Advantage plans can change their benefits, costs, provider networks, and drug formularies every year. A plan that worked perfectly this year might look very different next year. Your copays could increase, your favorite doctor might be dropped from the network, or a medication you depend on might no longer be covered.

This means you need to carefully review your plan during every Annual Enrollment Period (October 15 – December 7), which many beneficiaries find exhausting. In 2026, nearly 3 million Medicare Advantage enrollees had to find alternative coverage after plans reduced service areas or exited markets entirely.

5. Difficulty Switching Back to Medigap

This is what many experts call the “Medicare Advantage trap.” When you first become eligible for Medicare, you have a guaranteed right to purchase a Medicare Supplement (Medigap) plan without medical underwriting, meaning the insurance company can’t deny you coverage or charge more due to health conditions.

However, if you enroll in a Medicare Advantage plan and later decide to switch back to Original Medicare with a Medigap supplement, you may face medical underwriting. If you’ve developed health conditions while on Medicare Advantage, you could be denied Medigap coverage entirely, or face much higher premiums. Learn more about the process, timing, and state protections in our complete guide to switching from Medicare Advantage to Medigap.

This is critical information that many people don’t learn until it’s too late.

6. Doctors Don’t Always Like Them Either

It’s not just patients who have concerns. Many healthcare providers have frustrations with Medicare Advantage plans, including:

  • Lower reimbursement rates compared to Original Medicare
  • Slower payment processing from insurance companies
  • Administrative burden of prior authorization paperwork
  • Frequent claim denials that require time-consuming appeals

Some providers have stopped accepting certain Medicare Advantage plans altogether. If your doctor drops your plan’s network, you may face the difficult choice of switching doctors or switching plans.

Learn more about why doctors dislike Medicare Advantage plans

7. Marketing Tactics Can Be Misleading

The aggressive marketing around Medicare Advantage plans, especially during enrollment season, can create unrealistic expectations. TV commercials emphasize $0 premiums, grocery allowances, gym memberships, and dental benefits while glossing over network restrictions, prior authorization requirements, and potential out-of-pocket costs.

These extra benefits can be genuinely helpful, but they shouldn’t be the primary reason you choose a health insurance plan. A $50 monthly grocery allowance isn’t worth much if your plan denies coverage for a procedure you need.

When Medicare Advantage Plans Actually Work Well

Medicare advisor helping a beneficiary compare plan options
Working with an independent Medicare advisor can help you understand the trade-offs of each plan type.

Despite the legitimate criticisms, Medicare Advantage plans aren’t bad for everyone. They can be an excellent choice in the right circumstances.

You May Benefit from Medicare Advantage If:

  • You’re generally healthy and don’t visit doctors frequently. With low utilization, the $0 or low premium can save you significant money.
  • You live in a well-served area with robust provider networks. Urban areas tend to have many more in-network options.
  • You value bundled benefits like dental, vision, hearing, and prescription drug coverage in a single plan.
  • You stay in one geographic area and don’t travel extensively or split time between states.
  • Budget is a primary concern. The lower monthly premiums can make healthcare more affordable for people on tight fixed incomes, as long as they stay relatively healthy.
  • You’re willing to do annual homework. If you’re committed to reviewing your plan each year and switching if needed, you can stay ahead of changes.

The Satisfaction Numbers

It’s worth noting that many Medicare Advantage enrollees report being satisfied with their plans. When people choose a plan that genuinely fits their healthcare needs and geographic situation, and when they understand the rules going in, these plans can deliver real value.

The dissatisfaction tends to come from mismatched expectations, not from the plans being inherently “bad.”

Medicare Advantage vs. Medigap: A Fair Comparison

To truly understand whether Medicare Advantage is right for you, it helps to compare it directly with the alternative: Original Medicare paired with a Medigap (Medicare Supplement) plan. For a detailed comparison, see our guide on compare Medicare Advantage with Medigap. Learn more about Medigap Plan G.

Feature Medicare Advantage Original Medicare + Medigap
Monthly Premium Often $0 (plus Part B premium) Part B premium + Medigap premium ($100-$300+/mo)
Provider Choice Limited to plan network Any provider accepting Medicare nationwide
Out-of-Pocket Costs Copays, coinsurance as you go (max $9,250 in 2026) Predictable; Medigap covers most gaps
Referrals Required Yes (HMO plans) No
Prior Authorization Frequently required Rarely required
Extra Benefits Dental, vision, hearing, fitness often included Must purchase separately
Drug Coverage Usually included Separate Part D plan needed
Travel Coverage Limited to service area Nationwide
Annual Changes Benefits, networks, costs can change yearly Standardized benefits stay the same
Best For Healthy, budget-conscious, local care Frequent care needs, travelers, peace of mind

Not sure about your options? Read about deciding if you need a Medigap plan.

See our detailed Medicare Supplement vs. Advantage comparison guide

Compare Medicare Advantage vs. Supplement plans side by side

Compare Your Medicare Options with an Independent Advisor

Who Should Probably Avoid Medicare Advantage

Based on two decades of experience helping Medicare beneficiaries, there are certain situations where Original Medicare with a Medigap plan is likely the better choice:

  • You have chronic health conditions requiring regular specialist visits, frequent tests, or ongoing treatments. The copays and prior authorization requirements of Medicare Advantage can become costly and frustrating.
  • You travel frequently or spend significant time in different states. Medicare Advantage networks are typically local or regional.
  • You have established doctor relationships you’re not willing to change. Losing access to a trusted provider can disrupt your care.
  • You want predictable costs. If knowing exactly what you’ll pay each month matters more than having the lowest possible premium, Medigap offers that stability.
  • You’re concerned about future health. If you anticipate needing more care in coming years, locking in Medigap coverage during your initial enrollment period (when you can’t be denied) may be the safer long-term play.
Senior man researching Medicare coverage options on laptop
Taking time to research and compare your Medicare options is one of the best investments you can make in your healthcare.

How to Make the Right Decision for Your Situation

Rather than asking “are Medicare Advantage plans bad?” the better question is: “Which Medicare path is right for me?” Here’s a practical framework:

Step 1: Assess Your Health Needs

List your current doctors, specialists, medications, and how often you use healthcare services. If you have a complex medical situation, weigh the impact of network restrictions and prior authorization on your care.

Step 2: Calculate the True Cost

Don’t just compare monthly premiums. Add up estimated copays, deductibles, and potential out-of-pocket expenses for a typical year of your healthcare usage. A $0 premium plan can end up costing more than a $200/month Medigap plan if you use your coverage regularly.

Step 3: Check Provider Networks

Before enrolling in any Medicare Advantage plan, verify that your current doctors, specialists, and preferred hospitals are in-network. Use Medicare.gov’s Plan Finder tool to compare specific plans in your area.

Step 4: Consider Your Lifestyle

Do you travel? Split time between states? Plan to relocate in retirement? These factors heavily favor Original Medicare’s nationwide coverage over Medicare Advantage’s local networks.

Step 5: Talk to an Independent Medicare Advisor

An independent advisor (not one tied to a specific insurance company) can help you compare your specific options based on your health, budget, and location. They can walk you through the details that TV commercials leave out.

Learn how to compare Medicare Advantage plans effectively

Get Personalized Help Choosing the Right Medicare Plan

Frequently Asked Questions

Are Medicare Advantage plans really bad?

Medicare Advantage plans aren’t inherently bad, but they involve trade-offs that don’t work for everyone. The most common issues are network restrictions, prior authorization delays, and unpredictable out-of-pocket costs. For healthy people who stay local and understand the rules, they can be a cost-effective option. For those with complex health needs or who travel frequently, Original Medicare with a Medigap supplement may be the better choice.

Why do so many doctors dislike Medicare Advantage plans?

Doctors often report lower reimbursement rates, slower payments, excessive prior authorization paperwork, and frequent claim denials from Medicare Advantage plans. These issues can strain the doctor-patient relationship and lead some providers to stop accepting certain plans.

Can I switch from Medicare Advantage back to Original Medicare?

Yes, you can switch back during certain enrollment periods. However, if you want to add a Medigap supplement, you may face medical underwriting after your initial enrollment period has passed. This means you could be denied coverage or charged higher premiums based on your health history.

What is the maximum out-of-pocket cost for Medicare Advantage in 2026?

For 2026, Medicare Advantage plans can set their out-of-pocket maximum as high as $9,250 for in-network services. Some plans set lower maximums, so it’s important to check the specific plan you’re considering.

Is Medicare Advantage or Medigap better for someone turning 65?

It depends on your individual circumstances. If you’re healthy, live in an area with good networks, and want to minimize monthly premiums, Medicare Advantage may work well. If you want maximum flexibility, predictable costs, and the freedom to see any Medicare-accepting doctor nationwide, Medigap is typically the stronger choice. The key is making an informed decision during your initial enrollment period, when you have guaranteed access to Medigap plans.

The Bottom Line

Medicare Advantage plans aren’t universally “bad,” but they do come with real trade-offs that are frequently underexplained during the enrollment process. The common criticisms, including network limitations, prior authorization hassles, the nickel-and-dime cost structure, and the difficulty of switching back to Medigap, are all legitimate concerns worth understanding.

At the same time, these plans genuinely help millions of Americans access affordable healthcare coverage with benefits that Original Medicare doesn’t offer. The key is matching the right plan to your specific health needs, financial situation, and lifestyle.

The worst decision you can make is an uninformed one. Take the time to understand both options, compare the real costs (not just the premiums), and work with an independent Medicare advisor who can help you see the full picture.

Compare Original Medicare vs. Medicare Advantage to explore your options in detail.

This article was reviewed by Karl Bruns-Kyler, founder of The Big 65 Medicare Insurance Services, with over 20 years of experience helping Medicare beneficiaries make informed coverage decisions. Licensed in 33 states.


Medicare Advantage vs. Medigap: Which is Better?

What Is Medicare Advantage?

Medicare Advantage (Part C) is an all-in-one alternative to Original Medicare offered by private insurance companies approved by Medicare. When you enroll in a Medicare Advantage plan, you receive your Part A (hospital) and Part B (medical) benefits through a single private plan rather than directly from the federal government.

Need help choosing between Medicare Advantage and Medigap? Talk to a licensed Medicare expert at The Big 65 today.

Most Medicare Advantage plans also bundle Part D prescription drug coverage, and many include extras like dental, vision, hearing, and fitness benefits. The trade-off? You typically must use a network of doctors and hospitals (HMO or PPO), and some services may require prior authorization from your insurer.

As of early 2026, over 35 million Americans are enrolled in Medicare Advantage, representing roughly 51% of all eligible Medicare beneficiaries. The average beneficiary can choose from about 42 different plans in their area.

What Is Medigap (Medicare Supplement Insurance)?

Medigap, formally known as Medicare Supplement Insurance, works alongside Original Medicare rather than replacing it. You keep your Original Medicare Parts A and B, and your Medigap policy helps pay the “gaps” that Original Medicare leaves behind, including copayments, coinsurance, and deductibles.

Medigap plans are standardized by letter (Plan A, B, C, D, F, G, K, L, M, and N) in most states. A Plan G from one insurance company offers the same core benefits as a Plan G from another, though premiums may differ. Plan G is currently the most popular choice, covering nearly all out-of-pocket costs except the annual Part B deductible ($283 in 2026).

Importantly, Medigap does not include prescription drug coverage. If you choose the Medigap path, you’ll need a separate standalone Part D plan for your medications.

Medicare Advantage vs. Medigap: Key Differences at a Glance

The core difference comes down to structure: Medicare Advantage replaces Original Medicare with a bundled private plan, while Medigap supplements Original Medicare to fill coverage gaps. You cannot have both at the same time. Learn more about Medicare Supplement Plan G.

Feature Medicare Advantage (Part C) Medigap (Medicare Supplement)
How It Works Replaces Original Medicare with an all-in-one private plan Works alongside Original Medicare to cover out-of-pocket costs
Monthly Premium Often $0 beyond your Part B premium; average ~$17/month Varies by plan, state, and age; Plan G averages ~$164/month
Doctor Choice Must use plan’s network (HMO/PPO); may need referrals See any doctor or hospital nationwide that accepts Medicare
Out-of-Pocket Maximum Yes, annual cap (around $8,850–$9,250 for in-network in 2026) Minimal out-of-pocket costs; most plans cover nearly everything
Prescription Drug Coverage Usually included (bundled Part D) Not included; must buy a separate Part D plan
Dental, Vision, Hearing Often included Not included; must purchase separately
Prior Authorization Often required for certain services Not required; Original Medicare rules apply
Travel Coverage Usually limited to plan’s service area (except emergencies) Nationwide coverage; some plans cover foreign travel emergencies
Plan Stability Benefits can change annually; plans can leave your area Standardized benefits are guaranteed renewable and don’t change

Cost Comparison: What You’ll Actually Pay

Premium alone doesn’t tell the full story. Here’s a realistic breakdown of what each path may cost in 2026:

Cost Category Medicare Advantage Medigap + Part D
Part B Premium ~$202.90/month (required either way) ~$202.90/month (required either way)
Plan Premium $0–$17/month average $130–$250+/month (varies by plan, age, state)
Part D Premium Usually included ~$40–$50/month (separate plan)
Total Monthly Premium ~$202.90–$202 ~$355–$485+
Copays per Doctor Visit $20–$50 per visit $0 with most plans (Plan G: only Part B deductible)
Worst-Case Annual Out-of-Pocket Up to ~$8,850–$9,250 (MOOP cap) $283 Part B deductible + minimal costs

The bottom line: Medicare Advantage has lower monthly premiums but higher costs when you use services. Medigap has higher premiums but near-zero costs at the point of care. If you’re healthy and rarely see doctors, Medicare Advantage may save you money. If you have chronic conditions or use healthcare frequently, Medigap’s predictable costs can actually be less expensive in the long run.

Senior reviewing Medicare plan documents and comparing Medigap vs Medicare Advantage coverage options
Taking time to compare your Medicare options can help you find the best coverage for your health needs and budget.

Pros and Cons of Medicare Advantage

Pros

  • Low or $0 monthly premiums beyond your Part B premium
  • Bundled benefits: Drug coverage, dental, vision, hearing, and fitness often included
  • Out-of-pocket maximum: A built-in annual spending cap protects against catastrophic costs
  • Convenience: One card, one plan, one premium for most of your healthcare needs
  • Part B premium giveback: Some plans reduce your Part B premium amount

Cons

  • Network restrictions: You must use in-network doctors and hospitals for covered care
  • Prior authorization: Some treatments, tests, and specialist visits require insurer approval, which can delay care
  • Higher costs when sick: Copays accumulate with frequent doctor visits, potentially reaching thousands per year
  • Geographic limitations: Coverage is typically limited to a local service area
  • Annual plan changes: Benefits, networks, and formularies can change each year

Pros and Cons of Medigap

Pros

  • Predictable costs: After your premium, you pay little to nothing for covered services
  • Complete provider freedom: See any doctor or hospital in the U.S. that accepts Medicare, with no referrals needed
  • Guaranteed renewable: Your insurer cannot drop you as long as you pay your premium
  • Standardized plans: Benefits don’t change year to year; a Plan G is a Plan G everywhere
  • Travel-friendly: Nationwide coverage, and several plans include foreign travel emergency benefits

Cons

  • Higher monthly premiums: Expect $130–$250+ per month depending on your plan, age, and location
  • No drug coverage: You must purchase a separate Part D plan
  • No extras: Dental, vision, and hearing coverage must be purchased separately
  • Medical underwriting: Outside your initial 6-month Medigap Open Enrollment Period, insurers in most states can deny you or charge more based on health history

Who Should Choose Medicare Advantage?

Medicare Advantage may be the better fit if you:

  • Are generally healthy and don’t see doctors frequently
  • Want to keep monthly costs as low as possible
  • Value the convenience of bundled dental, vision, hearing, and drug coverage
  • Don’t travel extensively and are comfortable staying within a local network
  • Prefer one plan and one card for simplicity

Who Should Choose Medigap?

Medigap may be the better choice if you:

  • Have chronic conditions or see specialists regularly
  • Want the freedom to see any Medicare-accepting doctor without restrictions
  • Travel frequently between states or internationally
  • Prefer predictable healthcare costs with no surprises
  • Value long-term plan stability and don’t want to review plan changes annually

As Karl Bruns-Kyler, founder of The Big 65 and a licensed Medicare insurance broker with over 20 years of experience, often explains: “The right choice isn’t about which plan type is ‘better’ in the abstract. It’s about which one fits your health situation, budget, and lifestyle. A plan that works perfectly for your neighbor may not work for you.”

Let Karl and The Big 65 team help you find the right Medicare plan for your situation. Get started today.

Enrollment: When and How to Sign Up

Medicare Advantage Enrollment

You can enroll in a Medicare Advantage plan during:

  • Initial Enrollment Period (IEP): The 7-month window around your 65th birthday
  • Annual Enrollment Period (AEP): October 15 through December 7 each year
  • Medicare Advantage Open Enrollment Period: January 1 through March 31 (for those already in an MA plan)
  • Special Enrollment Periods: Triggered by qualifying life events like moving or losing employer coverage

Medigap Enrollment

Your best opportunity to enroll in a Medigap plan is during your 6-month Medigap Open Enrollment Period, which starts the month you turn 65 and are enrolled in Medicare Part B. During this window:

  • You have guaranteed-issue rights, meaning no insurer can deny you or charge more based on health conditions
  • You can choose any Medigap plan sold in your state

Critical warning: If you miss this window and later decide to switch from Medicare Advantage to Medigap, most states allow insurers to use medical underwriting. This means they can review your health history and potentially deny coverage or charge higher premiums. A few states (Connecticut, Massachusetts, New York, and others) offer protections, but for most people, the initial enrollment decision carries significant long-term weight. You may also want to read about potential downsides of Medicare Advantage.

Can You Switch Between Medicare Advantage and Medigap?

Technically, yes. You can drop a Medicare Advantage plan and return to Original Medicare during the Annual Enrollment Period (October 15 to December 7) or the MA Open Enrollment Period (January 1 to March 31).

However, the challenge is getting a Medigap policy after your initial enrollment window has closed. In most states, switching back means facing medical underwriting for Medigap, which can make this transition difficult or expensive if your health has changed. This is why it’s so important to carefully consider your initial choice and understand the long-term implications.

Ready to compare your Medicare options? Contact The Big 65 for free, personalized guidance from a licensed independent broker.

Frequently Asked Questions

Can I have both Medicare Advantage and Medigap at the same time?

No. You must choose one path or the other. If you have a Medicare Advantage plan, a Medigap policy will not pay for any services. You are either on the Medicare Advantage path or the Original Medicare + Medigap path.

Is Medicare Advantage really free?

Not exactly. While many Medicare Advantage plans have $0 plan premiums, you still pay your monthly Part B premium (~$202.90 in 2026). You also pay copays and coinsurance each time you use services, which can add up to thousands per year depending on your healthcare needs.

Which option is better for someone with a chronic illness?

For most people managing chronic conditions, Medigap combined with Original Medicare tends to offer better value. You get unrestricted specialist access without referrals, no prior authorization delays, and predictable costs regardless of how many appointments or treatments you need. The cost comparison changes significantly when you account for frequent copays under Medicare Advantage.

What is the most popular Medigap plan?

Plan G is the most popular Medigap plan in 2026, chosen by about 39% of Medigap enrollees. It covers nearly all out-of-pocket costs except the annual Part B deductible ($283 in 2026). Learn more about Medigap plan options and rate comparisons here.

Does Medigap cover prescription drugs?

No. Medigap plans do not include prescription drug coverage. If you choose Medigap, you’ll need to enroll in a separate Medicare Part D plan for your medications. Starting in 2026, the Inflation Reduction Act caps annual out-of-pocket drug costs at $2,000 under Part D, making this more affordable than in previous years.

What happens to my Medicare Advantage benefits if I move to a new state?

Medicare Advantage plans are tied to local service areas. If you move outside your plan’s area, you’ll qualify for a Special Enrollment Period to choose a new plan. However, the Medicare Advantage plans available to you will change based on your new location. With Medigap + Original Medicare, you have nationwide coverage and moving doesn’t affect your benefits.

Making Your Decision: A Step-by-Step Approach

  1. Assess your health needs. List your current doctors, specialists, prescriptions, and how often you use healthcare services.
  2. Check your doctors. If considering Medicare Advantage, verify that your preferred providers are in the plan’s network.
  3. Run the numbers. Compare total annual costs (premiums + expected out-of-pocket) for both paths based on your typical healthcare usage.
  4. Consider your lifestyle. Travel frequency, desire for provider flexibility, and comfort with network restrictions all matter.
  5. Think long-term. Your health may change. Consider what happens if you need more care in 5 or 10 years.
  6. Get expert guidance. A licensed, independent Medicare broker like The Big 65 can help you compare your specific options without bias toward any single insurance carrier.

If you’re still weighing whether a Medicare supplement is worth the cost, our decision guide on whether you need a Medicare supplement walks through the key factors, including a detailed cost analysis and Karl’s recommendation framework. For a focused side-by-side breakdown, see our Medicare Advantage vs. Supplement comparison page.

With over 20 years of Medicare expertise and licensing across 33 states, Karl Bruns-Kyler and The Big 65 team provide personalized, independent guidance to help you find the right coverage for your unique situation. Whether you’re leaning toward Medicare Advantage or Medigap, having an experienced advisor in your corner can help you avoid costly mistakes and make a confident decision.

For the full picture of what each part of Medicare costs in 2026, read our complete Medicare costs breakdown.

Don’t let stress stir up the hive 🐝😤

Hey there. May this blog find you better than ever, with your Medicare Insurance 🐝bee-having🌸🤣!

For Supplements, Medicare Advantage, or Part D Drug Plan questions or quotes, please e-mail Gray, Gray@TheBig65.com or book a time on my calendar .

Bees are like families… every hive is different. Two summers ago, inspecting without a bee suit would’ve been asking for trouble😠🐝.

Karl of The Big 65 inspecting his bee hive without a bee-keeping suite.

With so much rain and so much in bloom this summer, the girls are filling their pockets with pollen and everybody’s happy, oblivious to my prodding, poking, and inspections.

Keep your fingers crossed for a good harvest🤞. Please let me know if we still owe you honey for a referral🍯, or a Google review.

Karl Bruns-Kyler working with his bee-hive while thinking about Medicare.

Stress is a normal part of living, and some stress is beneficial, but…

Living with chronic stress wears down the body, the mind, and the soul. It can also harm relationships.

Just ask Elwood, the 10 year old rescue Rottie who went from super stressed (with many bad habits) to extra happy camper now living with our daughter Sus.

There is hope if we learn to recognize and handle the triggers.

Elwood, the 10 year old rescue Rottie, looking through iron gates.

As we age, the ability to bounce back from stress decreases. What once felt like a bump — a delayed prescription or a noisy neighbor—can suddenly feel like a kick in the butt.

Research shows long-term stress can weaken the immune system, increase inflammation, and even accelerate memory loss.

Nobody wants to feel like an old turkey🦃👴.

Two wild turkeys scratching for food.

But here’s the hopeful news: stress doesn’t have to control our lives.

Like bees in a healthy hive, we function best when we’re nourished, connected, and not under attack.

Managing stress is all about finding daily practices that bring calm, purpose, and resilience.

Plato says if that includes brushing him, so be it😇!

Quantz brushing Plato the big black and white dog.

Here are a few simple ways to keep your “inner hive” calm:

  • 🐝 Start the morning quietly – even 5 minutes of breathing or sipping tea without a screen helps.

  • 🚶 Get outside daily – movement and fresh air regulate cortisol levels.

  • 📞 Connect with someone – a short call or walk with a friend reduces stress hormones.

  • 🛏️ Protect your sleep – it’s the ultimate reset button.

  • 📚 Unplug and recharge – books, puzzles, and hobbies calm a buzzing brain.

Mark and Carrie have celebrated the last 8 Summer 🌞 Solstices together, usually on their bikes and with a bottle of champagne. They were kind enough to share a glass with me🥂🍾  on the trail.

A man holding a bottle of champagne as a lady watches him hold the bottle.

If stress is affecting your health, it could influence your Medicare needs too. Plans change annually, and so do your priorities. Let’s make sure your coverage is aligned with the life you want to live.

It’s all about small changes, giving thanks for what’s actually working in our lives: family, friends, service, and laughter. Don’t focus on the small bumps, enjoy the ride.

Try to be like Rocky. When her last dog died, she thought it was too late to have another. Coming home to an empty house after a visit to the kids convinced her she needed another.

Say hello to rescue Olivia👏🎉, the joy of her life (and the joy of her neighbors when she goes on vacation and they get to babysit Olivia).

It’s never too late to find love❤️.

A nice lady walking her dog.

Keep squeezing the juice🍊 out of life and look for ways to help others.

If family or friends need help… referrals are the lifeblood of my business.

If you know someone who might like to receive The Big 65 newsletter, forward this link.

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@theBig65.com.

Let us know what’s going on and please send pictures :).

Karl Bruns-Kyler
(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in thirty states around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Kentucky
Louisiana
Maryland
Michigan
Minnesota
Missouri
Montana
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Medicare Broker Karl Bruns-Kyler and Plato the big black and white dog.


Medigap Plan G vs. N: Which Prevents Surprise Bills?

Choosing a Medigap plan is really about one thing: financial peace of mind. You know Original Medicare is a solid foundation, but it leaves gaps that can lead to unpredictable medical bills. That’s where Medigap comes in. For most new Medicare members, the decision boils down to a medicare supplement plan g vs n comparison. If you’re thinking, “I’m okay with higher premiums if it means fewer surprise bills—should I go with Medigap Plan G or N?”, you’re asking the exact right question. This guide will give you the clear comparison you need to answer it confidently.

Key Takeaways

  • Decide on Your Financial Comfort Zone: Plan G offers maximum coverage for a higher monthly premium, meaning fewer surprise bills. Plan N lowers your monthly payment but requires you to handle small, predictable copays for doctor visits.
  • Shop Around for the Best Price: Since Medigap plans are standardized, a Plan G is a Plan G everywhere. The main difference is the price, so comparing quotes from different insurance companies is the best way to save money on your monthly premium.
  • Choose for the Long Haul: Your first Medigap choice is critical, as switching plans later may be difficult. Select a plan based not just on your current health, but on the financial security you want for years to come.

What Is a Medigap Plan?

Think of Original Medicare (Parts A and B) as your foundational health coverage. It’s a fantastic starting point, but it doesn’t cover everything. You’re still responsible for certain costs like deductibles, copayments, and coinsurance. This is where Medigap plans, also known as Medicare Supplement Insurance, come into the picture. These plans are offered by private insurance companies and are designed to work with Original Medicare to help pay for some of those remaining costs.

The reason these plans exist is because Original Medicare has “gaps” in its coverage. For example, after you’ve met your annual deductible, Medicare Part B generally only covers 80% of the cost for most doctor services and outpatient care. You are responsible for the remaining 20%, which can add up quickly, especially if you need frequent medical care. A Medigap plan can help cover that 20% coinsurance, giving you more predictable healthcare expenses.

To make comparing plans easier, the government standardized them. There are 10 standardized Medigap plans available in most states, each identified by a letter (A, B, C, D, F, G, K, L, M, and N). This means that a Plan G from one insurance company must offer the same basic benefits as a Plan G from any other company. The main differences you’ll find are the monthly premium and the quality of the company’s customer service. This standardization allows you to shop for the best price without worrying that you’re getting lesser coverage. Ultimately, the goal of a Medigap plan is to help pay out-of-pocket costs and provide you with financial peace of mind.

Eligibility: Original Medicare Is a Must

Before you can even begin to compare Medigap plans, there’s a fundamental requirement you must meet. As noted by Healthline, “To get a Medigap plan, you must have Original Medicare.” This isn’t just a suggestion; it’s the first and most important step. Medigap plans are specifically designed to supplement the coverage provided by Medicare Part A (hospital insurance) and Part B (medical insurance). They work in tandem with Original Medicare to cover costs like your 20% coinsurance and various deductibles. Without Part A and Part B in place, a Medigap plan has nothing to supplement, making it essential to secure your foundational Medicare coverage first.

What This Means for You

Simply put, your first action item is to ensure you are enrolled in both Medicare Part A and Part B. For most people, this happens during their Initial Enrollment Period, the seven-month window around their 65th birthday. If you’re already past that period, you may need to wait for the General Enrollment Period to sign up. Once your Original Medicare is active, you can then apply for a Medigap plan. Think of it as building a house: Original Medicare is the foundation, and a Medigap plan is the framework that provides extra support and protection.

Medigap vs. Medicare Advantage: You Can Only Have One

One of the most common points of confusion for new Medicare members is the difference between Medigap and Medicare Advantage (also known as Part C). The most important rule to remember is that you cannot have both at the same time. As GoodRx clearly states, “You cannot have a Medigap plan if you are already enrolled in a Medicare Part C (Advantage) plan.” These two options represent two very different paths for your healthcare coverage. Medigap works *with* Original Medicare, while Medicare Advantage *replaces* it. Choosing a Medicare Advantage plan means you’ll get your Part A and Part B benefits through a private insurance company, often with a specific network of doctors and hospitals.

Freedom of Choice: See Any Doctor Who Accepts Medicare

A significant benefit of choosing a Medigap plan is the freedom it offers. With any Medigap plan, including Plan G and Plan N, you can see any doctor or specialist and visit any hospital in the United States, as long as they accept Medicare. There are no network restrictions, and as one expert explains, “You don’t need referrals.” This flexibility is a major draw for people who travel frequently or want to ensure they can continue seeing their trusted doctors without worrying if they are “in-network.” This level of choice gives you control over your healthcare decisions, allowing you to focus on getting the best care possible, wherever you are.

Guaranteed for Life: Your Coverage Is Secure

One of the greatest sources of peace of mind that comes with a Medigap plan is its stability. Once you are enrolled, your plan is guaranteed renewable for life. This means the insurance company cannot cancel your policy for any reason, including changes in your health, as long as you continue to pay your premiums. The benefits of your plan are also locked in and will not change. This assurance is invaluable, especially if you develop a chronic condition. While your monthly premium may increase over time due to inflation or age, you can rest easy knowing your core coverage is secure and will be there when you need it most.

What Medigap Doesn’t Cover

While Medigap plans are excellent for covering the “gaps” in Original Medicare, it’s just as important to understand what they don’t cover. According to Healthline, “Medigap plans do NOT cover things like dental care, hearing aids, eyeglasses, or most prescription drugs.” To get coverage for your medications, you will need to enroll in a separate, standalone Medicare Part D prescription drug plan. This is a critical piece of the puzzle for managing your total healthcare costs. Putting together the right combination of plans can feel complex, which is why our team at The Big 65 is dedicated to helping clients find the right Part D plan that fits their specific prescription needs.

Do You Really Need a Medigap Plan?

If you’re enrolled in Original Medicare, you have solid hospital and medical coverage. But it’s important to know that Original Medicare doesn’t cover everything. It leaves behind certain “gaps” that you are responsible for paying, like deductibles, copayments, and coinsurance. This is where a Medigap plan, also known as Medicare Supplement Insurance, can be a lifesaver. These plans are offered by private insurance companies and are specifically designed to help pay for those remaining costs.

Think about it this way: Medicare Part B typically covers 80% of your outpatient medical expenses after you’ve met your deductible. That means you’re on the hook for the other 20%, and there’s no annual cap on how high that amount can go. If you have a chronic condition or need frequent medical care, that 20% can add up to a significant financial burden over the year. A Medigap plan can cover some or all of that remaining share, protecting your budget from unpredictable medical bills. This is especially crucial for anyone who anticipates needing ongoing treatment, as these out-of-pocket costs can be substantial.

Beyond the practical financial help, a Medigap plan provides invaluable peace of mind. Worrying about how you’ll afford care during a health crisis is the last thing you need. For instance, while Medicare Part A covers hospital stays, its coverage has limits, and a prolonged stay could result in large bills. Having a Medigap plan means you have a predictable, manageable way to handle these costs, allowing you to focus on what matters most—your health. Because everyone’s needs and budget are unique, it’s wise to compare different Medigap options to find the one that best fits your personal situation.

Breaking Down Your Medigap Plan Options

When you start looking at Medigap, you’ll see plans labeled with letters, like Plan G or Plan N. These plans are standardized by the government, which is great news for you. It means that a Plan G from one company has the exact same basic benefits as a Plan G from another. The main difference you’ll find is the price, or the monthly premium, that each insurance company charges.

While there are 10 different Medigap plans available, most people find that just a few of them offer the right mix of coverage and value. The two most popular choices for new Medicare members are Plan G and Plan N. They’ve become the go-to options because they provide substantial coverage without the highest possible price tag.

You might have heard friends or family talk about Plan F, which was once the most comprehensive plan. However, Plan F is no longer available to anyone who became eligible for Medicare on or after January 1, 2020. Because of this change, Plan G has stepped into the spotlight as the most extensive coverage you can get as a new enrollee. Understanding the differences between these top plans is the first step toward finding the one that fits your life and budget.

A Note on State-Specific Plans

How Plans in MA, MN, and WI Differ

While the standardized letter system makes comparing Medigap plans straightforward in most of the country, it’s important to know that three states march to the beat of their own drum: Massachusetts, Minnesota, and Wisconsin. If you live in one of these states, you won’t find the typical Plan G or Plan N. Instead, these states have their own unique Medigap plans with different structures and benefits. For example, Massachusetts offers a Core Plan and two supplement plans, while Minnesota and Wisconsin also have their own distinct offerings. This means the coverage details you read about for the standard lettered plans won’t apply directly to you. Because these plans are structured differently, it’s essential to look at the specific options available in your state to make an informed choice. This is one area where getting guidance from an independent agent who is licensed in your state can make a world of difference, ensuring you understand exactly what you’re buying.

Plan G: The Go-To for Comprehensive Coverage

Think of Plan G as the new heavyweight champion of Medigap. For anyone new to Medicare, it offers the most coverage you can buy. It covers nearly all of your out-of-pocket costs that Original Medicare leaves behind, including copayments and coinsurance. The only thing you’re responsible for is the annual Medicare Part B deductible. Once you’ve paid that for the year, Plan G takes care of the rest for Medicare-approved services.

A key feature of Plan G is that it covers Part B excess charges. These are extra fees that some doctors can charge above the Medicare-approved amount. While not all doctors apply these charges, having them covered gives you an extra layer of financial protection. Because of its comprehensive nature, Medicare Supplement Plan G typically comes with a higher monthly premium, but for many, the peace of mind is well worth it.

How Popular Is Plan G?

It’s no surprise that Plan G has become the leading choice for new Medicare beneficiaries. In fact, it’s currently the most popular Medigap plan, making up the vast majority of new policies sold. People gravitate toward Plan G because it offers a straightforward promise: once you pay your monthly premium and meet the annual Part B deductible, your Medicare-approved costs are covered. This level of predictability is incredibly valuable. It removes the guesswork and worry about what a doctor’s visit or hospital stay might cost, allowing you to budget effectively and focus on your health without the shadow of unexpected medical bills.

High-Deductible Plan G: A Lower-Premium Alternative

For those who are comfortable with taking on more initial risk in exchange for a lower monthly payment, there’s High-Deductible Plan G. This plan offers the same coverage as the standard Plan G, but only after you’ve paid a significant annual deductible. For 2024, this deductible is $2,800. This means you are responsible for all your Medicare-approved costs—including deductibles, copays, and coinsurance—until you reach that amount. After that, the plan pays 100%. This option can be appealing if you are in good health and don’t anticipate needing frequent medical care, as the lower monthly payments can lead to substantial savings. However, you must be financially prepared to cover that high deductible if a health issue arises.

Plan N: The Savvy, Lower-Premium Choice

If you like the idea of strong coverage but want a lower monthly premium, Plan N is an excellent alternative. It provides much of the same protection as Plan G but asks you to share a small portion of the costs. In exchange for that lower premium, you’ll pay a copayment of up to $20 for some doctor’s office visits and a $50 copay for emergency room visits (which is waived if you’re admitted to the hospital).

The main difference between Plan N vs. Plan G is that Plan N does not cover Part B excess charges. This means if your doctor charges more than the Medicare-approved amount, you would be responsible for that difference. For individuals who don’t visit the doctor often and are comfortable with small, predictable copays, Plan N can be a smart way to save money each month without sacrificing major medical coverage.

How Popular Is Plan N?

Plan N has quickly become a favorite for many people new to Medicare, and it’s easy to see why. It strikes a fantastic balance between solid coverage and a more affordable monthly premium. For those who are generally healthy and don’t anticipate frequent doctor visits, Plan N offers a practical way to keep monthly costs down. The trade-off is simple: you agree to handle small, predictable copayments for certain services. This cost-sharing model is what makes the lower premium possible, and for many, it’s a worthwhile exchange. It’s often a great choice if you want to manage your healthcare expenses effectively while still having robust protection against major medical bills.

Are There Other Plans to Consider?

While G and N get most of the attention, it’s helpful to know a few other options exist. Plans K and L are designed with more cost-sharing. They have lower monthly premiums, but you pay a percentage of your medical costs until you reach a set out-of-pocket maximum for the year. Once you hit that limit, the plan covers 100% of your approved services for the rest of the year.

On the other end of the spectrum, Plans A and B offer more basic benefits and generally leave you with higher out-of-pocket expenses. And as mentioned, Plan F is still available for those who were eligible for Medicare before 2020. Knowing about the full range of the best Medigap plans can help you feel confident that you’re making a well-rounded decision.

Why Aren’t Other Plans as Popular?

You might wonder why the spotlight is so heavily on Plans G and N when other options exist. The simple answer is that other plans often don’t hit that perfect balance of coverage and cost for most people. For example, Plans A and B provide more basic benefits, which can leave you with significant out-of-pocket expenses—the very thing you’re trying to avoid by getting a supplement. On the other hand, Plans K and L have lower premiums but require you to share the costs by paying a percentage of your medical bills until you reach a high annual out-of-pocket limit. This model can feel risky, as a serious health issue could lead to substantial costs. Most people find that the comprehensive coverage and predictable costs of Plans G and N offer greater peace of mind.

Medigap Plan G vs. Plan N: A Head-to-Head Look

When you start looking at Medigap plans, you’ll quickly notice that Plan G and Plan N are two of the most popular options for new Medicare members. Both offer fantastic coverage, but they work a little differently. Think of it like choosing between a car with all the bells and whistles and one that’s just as reliable but has a few fewer features to keep the price down. Let’s break down the key differences so you can see which one aligns better with your needs and budget.

How Their Coverage Compares

Both Plan G and Plan N are designed to cover the “gaps” in Original Medicare, but they don’t cover the exact same things. Plan G is the most comprehensive plan available to new beneficiaries. Once you meet your annual Part B deductible, Plan G covers nearly all of your remaining out-of-pocket costs, including coinsurance and copayments. It’s a popular choice for people who want predictable healthcare expenses and minimal bills after receiving care.

Plan N also provides excellent coverage but asks you to share some of the costs. In exchange for a lower monthly premium, you agree to pay small copayments for certain services. It covers your Part A and B coinsurance but leaves you with a few predictable costs, which we’ll get into next.

What Both Plans Cover

Both Plan G and Plan N are designed to fill the financial gaps in Original Medicare, but they approach it a little differently. Plan G is the most comprehensive option available to new members. The way it works is simple: after you pay your annual Part B deductible, Plan G covers nearly all of your remaining out-of-pocket costs for Medicare-approved services. This makes it a popular choice for anyone who values predictable healthcare expenses and wants to avoid surprise bills.

Plan N offers strong coverage for a lower monthly premium, but it requires you to share some costs. You’ll have small copayments—up to $20 for some doctor visits and $50 for the ER. The most important distinction is that Plan N does not cover Part B excess charges, which are extra fees some doctors can bill. If your doctor applies these, you’ll be responsible for them. You can compare these details to see which fits best. The choice depends on your comfort level. Plan G offers maximum coverage, while Plan N is a savvy way to save on premiums if you’re okay with small copays. This helps you determine if Plan G is worth the extra cost for the security you want.

How Do Monthly Premiums Stack Up?

The monthly premium is often the first thing people look at, and it’s one of the biggest differences between these two plans. Because it offers more first-dollar coverage, Plan G generally has a higher monthly premium than Plan N. You’re paying a bit more each month for the peace of mind that comes with having fewer out-of-pocket expenses when you need care.

On the other hand, Plan N was designed to be a more budget-friendly option. Its lower monthly premium is its main attraction. If you’re looking to keep your fixed monthly costs down and are comfortable paying for some services as you use them, the savings from Plan N’s premium can really add up over the year.

Average Monthly Premiums

When comparing costs, you’ll find that Plan N’s monthly premium is consistently lower than Plan G’s. This difference can be significant. For example, for a 65-year-old in Atlanta, a Plan G might cost around $119 per month, while a Plan N could be closer to $90. That’s a savings of nearly $350 a year right off the bat. Of course, these costs can vary widely based on your age, gender, and where you live. Because the benefits of each lettered plan are standardized, the only difference between a Plan G from Company X and Company Y is the price. This is why shopping around is so important. Working with an independent agency like The Big 65 can help you compare quotes from multiple carriers to ensure you’re not overpaying for your coverage.

Understanding the Part B Premium

It’s crucial to remember that your Medigap premium is paid *in addition* to your monthly Medicare Part B premium. Everyone enrolled in Medicare Part B must pay this premium, which goes directly to the government. This cost is set each year and is not covered by any Medigap plan sold to new enrollees. Similarly, both Plan G and Plan N require you to pay the annual Part B deductible yourself before your Medigap coverage kicks in. Think of your total monthly healthcare cost as your Part B premium plus your Medigap premium. For Plan N, you’ll also want to budget for the potential copays for doctor and ER visits.

What Are the Potential Out-of-Pocket Costs?

This is where the trade-off for Plan N’s lower premium becomes clear. With Plan N, after you’ve met your annual Part B deductible, you will have a copayment of up to $20 for some doctor’s office visits and a $50 copay for emergency room visits. It’s important to know the ER copay is waived if you’re admitted to the hospital. These costs are predictable and relatively small, but they are something to factor into your budget.

With Plan G, you don’t have these copayments. Once your Part B deductible is paid for the year, your plan covers these costs completely. This is the primary reason for its higher premium—it offers more complete coverage at the point of service.

The Annual Part B Deductible

Here’s a key point for both plans: you are responsible for paying the annual Medicare Part B deductible. This is the amount you pay out-of-pocket each year for doctor visits and other outpatient care before your Medigap plan’s main coverage begins. For Plan G, this is essentially the only major cost you’ll handle. As NerdWallet highlights, “The only thing you’re responsible for is the annual Medicare Part B deductible.” Once you’ve paid it, Plan G steps in to cover your Medicare-approved costs for the rest of the year. Plan N also requires you to meet this deductible, but remember, you will still have your small copays for office and ER visits afterward.

The Part A Hospital Deductible

The Medicare Part A deductible can be a source of major anxiety. This is the amount you must pay for a hospital stay during each benefit period, and it can be a significant expense. Here’s the great news: both Plan G and Plan N cover this deductible completely. This is a critical benefit that offers substantial financial protection against the high costs of hospitalization. Even though Plan N comes with small copays for doctor visits, it still provides powerful coverage where it often matters most. As ValuePenguin confirms, Plan N “covers your Part A deductible and coinsurance (hospital costs),” ensuring that a necessary hospital stay won’t leave you with a large, unexpected bill.

The Deal with Part B Excess Charges

Here’s a detail that can be a deciding factor for some. A Part B excess charge is an extra amount, up to 15%, that a doctor can legally charge you above the Medicare-approved amount for a service. It’s important to know that these charges are not very common, as most doctors in the country accept Medicare assignment, meaning they agree to take the Medicare-approved amount as full payment.

However, if you see a doctor who doesn’t accept assignment, the difference in coverage matters. Plan G covers Part B excess charges, so you’d never have to worry about them. Plan N does not cover these charges, meaning you would be responsible for paying them yourself if they occurred.

How Common Are Excess Charges?

Thankfully, Part B excess charges are not something most people will encounter. The vast majority of doctors and healthcare providers across the country accept Medicare assignment, which means they’ve agreed to accept the Medicare-approved amount as their full payment and won’t bill you for more. Still, you might find a provider who doesn’t accept assignment, which would leave you responsible for that extra 15% if you have Plan N. It’s also helpful to know that some states have laws that prohibit doctors from billing for excess charges, making this a non-issue for residents there. For everyone else, deciding between Plan G and Plan N on this point comes down to your personal comfort with this small but potential risk.

Which Plan Fits Your Lifestyle?

Choosing between Plan G and Plan N comes down to your personal preferences, health, and budget. If you value predictability and want to minimize out-of-pocket costs when you visit the doctor, Plan G is an excellent choice. You’ll pay a higher premium, but you’ll have very few other costs for Medicare-covered services.

If you are in good health, don’t anticipate frequent doctor visits, and want to save money on your monthly premiums, Plan N could be a great fit. The potential copayments might be a small price to pay for the significant monthly savings. It’s a matter of weighing the lower premium against the possibility of small, predictable out-of-pocket costs.

How to Approach Medigap Costs

When you start looking at Medigap plans, the price tag is often the first thing you notice. But the monthly premium is only one part of the story. Understanding what goes into that number and how it relates to your total healthcare spending is key to making a smart decision. It’s not just about finding the cheapest plan today, but about finding the one that offers financial predictability and peace of mind for the years ahead. Let’s break down how to think about these costs so you can feel confident in your choice.

What Factors Influence Your Premium?

You might notice that the monthly premium for the exact same Medigap plan can vary quite a bit. That’s because several personal factors influence your rate. Insurance companies look at your age, where you live, and whether you use tobacco. For example, living in a state with a higher cost of living or more expensive healthcare services can result in a higher premium. Your age when you first enroll also plays a significant role in setting your initial price. Because these factors can lead to substantial differences in what you pay, it’s important to compare Medigap plans carefully to see what rates you qualify for based on your personal situation.

How Will Your Premiums Change Over Time?

It’s helpful to think of Medigap costs as a balancing act between your monthly premium and your potential out-of-pocket expenses. A plan with a higher monthly premium, like Plan G, often comes with lower or no costs when you see a doctor or visit a hospital. On the other hand, a plan with a lower premium, like Plan N, might require you to pay a small copay for certain services. When you evaluate your healthcare needs, consider your health history and how often you anticipate needing medical care. This will help you decide which approach is more cost-effective for you in the long run—paying more each month for predictability or paying less upfront with some variable costs.

How to Research Rate Increase History

A low monthly premium today doesn’t guarantee an affordable plan tomorrow. It’s a fact of life that Medigap premiums increase over time, influenced by inflation and rising healthcare costs. The real question isn’t if your premium will go up, but by how much. A plan with a cheap initial rate might have a history of steep, frequent price hikes, making it less stable in the long run. Before you enroll, it’s wise to ask the insurance company for the plan’s rate increase history over the last five to ten years. This data can be difficult to track down on your own, which is where an experienced independent agent can be a huge help. At The Big 65, we can access this historical data to help you compare plans from different companies and find one with a record of more stable and predictable rate adjustments.

A Look at Plan G and Plan N Premium Trends

When you compare Plan G and Plan N, you’ll see a clear difference in their premium structures. Plan G is known for its comprehensive coverage, which means it typically has a higher monthly premium. In return, it covers nearly all of your out-of-pocket costs after you’ve met your Part B deductible. Plan N usually has a more moderate premium, making it an attractive option if you want to keep your fixed monthly expenses lower. However, with Plan N, you should be prepared for some additional costs, like a copay of up to $20 for doctor visits and a $50 copay for ER visits that don’t result in hospital admission. The choice really comes down to your budget and comfort with these potential out-of-pocket payments.

Why Plan N Premiums May Rise Slower

When you’re planning for the long term, it’s wise to consider how your monthly premium might change down the road. While no one can predict the future with certainty, there’s a strong trend suggesting Plan N premiums may rise more slowly than Plan G’s. The reason is tied to the plan’s design. Because Plan N requires you to pay small copayments for doctor visits, it tends to appeal to people who are in relatively good health. This creates a healthier group of members, or “risk pool,” who generally file fewer claims. Since insurance companies set future rates based on past claims, a healthier group often leads to smaller, more predictable rate increases over time.

How to Choose Between Medigap Plan G and N

Picking the right Medigap plan feels like a huge decision, because it is. But it doesn’t have to be overwhelming. The best plan for you comes down to a few key factors: your health, your budget, and how you feel about handling potential costs down the road. By thinking through these areas, you can find a plan that gives you security and peace of mind. Let’s walk through the four main questions to ask yourself.

Assess Your Current Health Needs

First, take an honest look at your health. This is the foundation for your decision. Think about how often you currently visit the doctor or specialists. Do you have any chronic conditions that require regular care? While no one has a crystal ball, you should “consider your current health, [and] potential future needs,” as you choose your coverage. If you see doctors frequently or manage an ongoing health issue, a plan with more comprehensive coverage, like Plan G, might be a better fit. This initial step helps you match a plan’s benefits to your real-world health situation.

Figure Out What Your Budget Allows

Next, it’s time to think about your finances. Your monthly premium is a fixed cost, but you also need to account for potential out-of-pocket expenses like deductibles and copayments. It’s a balancing act. For example, “Plan G may have higher monthly premiums compared to other plans like Plan N,” but it covers more, leaving you with fewer surprise bills. On the other hand, “Plan N generally has lower monthly premiums,” which can be great for your monthly budget, but you’ll be responsible for small copays for doctor and ER visits. Think about what you’re more comfortable with: a higher predictable monthly bill or a lower one with some variable costs.

A Quick Cost-Benefit Example

Let’s put this into perspective with a simple scenario. Imagine Plan N’s monthly premium is $40 less than Plan G’s in your area. Over a year, that’s a savings of $480. That’s a significant saving, but with Plan N, you have to account for potential copays. After you meet your Part B deductible, you’ll have a copayment of up to $20 for some doctor visits. If you divide your annual premium savings ($480) by that $20 copay, you get 24. This means if you anticipate having more than 24 doctor visits in a year, the higher premium for Plan G might actually be the more cost-effective choice. If you expect fewer visits, the monthly savings from Plan N are hard to ignore. This simple calculation helps you see how your health habits can directly influence which plan makes the most financial sense and is a great way to compare Plan G and Plan N for your specific needs.

Think About Your Long-Term Health

While your current health is a great starting point, it’s wise to plan for the future, too. Your health needs can change over time, and it’s not always easy to switch Medigap plans later on. Outside of your initial enrollment period, insurance companies can use medical underwriting to decide whether to cover you and how much to charge. This makes your first choice incredibly important. You should “carefully consider your healthcare usage, budget, and risk tolerance when choosing a plan” to ensure it serves you well for years to come. A plan that feels right today should also feel right if your health needs change tomorrow.

How Comfortable Are You with Financial Risk?

Ultimately, this choice comes down to your personal comfort with financial risk. Are you someone who sleeps better at night knowing that nearly all of your medical costs are covered after you meet your deductible? If so, Plan G’s comprehensive coverage is likely your best bet. Or, are you generally healthy and prefer to pay lower monthly premiums, even if it means handling some out-of-pocket costs yourself? If you “don’t anticipate frequent doctor visits or emergency room trips, Plan N could be a cost-effective option.” There’s no right or wrong answer—only the one that aligns with your personal and financial preferences.

Common Medigap Myths You Can Ignore

When you’re trying to figure out Medigap, it feels like everyone has an opinion. Friends, neighbors, and articles you find online might offer advice, but sometimes that information is outdated or just plain wrong. It’s easy to get tripped up by hearsay. Let’s walk through some of the most common myths about Medigap plans so you can separate fact from fiction and make a choice that feels right for you.

Myth: “All Medigap plans are the same.”

This is a common point of confusion, and it’s easy to see why. The truth is a little more nuanced. While Medigap plans are standardized by the government, they aren’t all the same. There are 10 distinct plans, labeled with letters like G and N, each offering different levels of coverage. The key thing to remember is that a Plan G from one company must offer the exact same benefits as a Plan G from another. What isn’t identical is the price. Insurance companies can charge very different monthly premiums for the same lettered plan, which is why it’s so important to compare your options carefully.

Myth: “Plan F is still the best plan available.”

You may hear friends or family who have been on Medicare for a while talk about how great Plan F is. And they’re not wrong—it was famous for its comprehensive coverage. However, a federal law changed things for new enrollees. If you became eligible for Medicare on or after January 1, 2020, you can no longer purchase Plan F. For anyone new to Medicare, Plan G is now the go-to choice and a strong alternative that offers nearly identical coverage. The only significant difference is that you have to pay your annual Part B deductible yourself with Plan G.

Myth: “With Plan G, you’ll have zero out-of-pocket costs.”

Plan G is incredibly popular because it covers so many of the gaps in Original Medicare, but it doesn’t eliminate all costs. With Plan G, your main out-of-pocket expense will be the annual Part B deductible. This is the amount you pay for doctor visits and other outpatient services before Medicare and your Medigap plan start paying their share. For many people, this is a predictable and manageable expense. Once you’ve met that deductible for the year, Plan G picks up the rest of the approved costs, including things like Part B excess charges, which can be a relief for your budget.

Myth: “Plan N only has small copays.”

Plan N is an attractive option because its monthly premiums are often lower than Plan G’s. While it’s true that you’ll have small copayments—up to $20 for some doctor’s office visits and $50 for an ER visit—that isn’t the whole story. The most important detail to understand about Plan N is that it does not cover Part B excess charges. These are extra fees that some doctors are legally allowed to charge above the Medicare-approved amount. While not all doctors bill for them, if you see one who does, you’ll be responsible for paying that difference out of pocket. This is a key trade-off for the lower premium.

How to Find the Best Rate for Your Medigap Plan

Once you have a good idea of whether Plan G or Plan N is a better fit for you, the next step is to find the best price. Since private insurance companies sell Medigap plans, the premiums for the exact same plan can be different from one company to the next. Think of it like buying a car—the same make and model can have different price tags at different dealerships. Your job is to find the one that offers the coverage you need at a price that works for your budget.

Finding the right rate involves a little bit of research, but it’s well worth the effort. By comparing your options, understanding what goes into the price, and asking the right questions, you can feel confident that you’re not overpaying for your coverage. Let’s walk through a few simple steps to help you secure a great rate for your Medigap plan.

Always Compare Quotes from Multiple Insurers

You wouldn’t buy the first house you see, and the same principle applies here. Because prices and plans vary between companies, it’s essential to get multiple quotes. This allows you to compare not just the monthly premium but also the company’s reputation for customer service and rate stability. An independent insurance agent can be a huge help here, as they can pull quotes from several different carriers for you all at once. This saves you the time and hassle of calling each company individually and gives you a clear, side-by-side look at your options.

Why an Independent Agent Can Help

While you can certainly call each insurance company yourself, the process can be time-consuming. This is where working with an independent agent can make a world of difference. Unlike a captive agent who only represents one company, an independent agent works with many different insurance carriers. Their job is to shop the market on your behalf, presenting you with the best options for your specific needs and budget. This approach saves you from making dozens of phone calls and filling out multiple forms. An experienced agent can quickly compare quotes for the same plan from various companies, but they also bring valuable insight into factors beyond price, like a company’s history of rate increases and its reputation for customer service. This expert guidance helps ensure you find a plan that offers both a competitive premium today and stability for the future.

Know the Three Ways Plans Are Priced

Monthly premiums for Medigap plans can change quite a bit based on your age, where you live, and whether you use tobacco. For instance, the cost for a Medigap Plan G in one city might be very different from the cost in another, even for the same person. Insurance companies use one of three pricing methods: community-rated, issue-age-rated, or attained-age-rated. Understanding which method a company uses is key, as it affects how your premium might change over time. Attained-age-rated plans, for example, often start with lower premiums that increase as you get older.

Community-Rated

With a community-rated plan, everyone in a specific area pays the same monthly premium, no matter how old they are. This means a 65-year-old and an 85-year-old with the same plan from the same company will have the same rate. While you might pay a little more when you first enroll compared to other pricing models, the big advantage is that your premium won’t go up just because you have a birthday. Your rate can still increase due to inflation or rising healthcare costs that affect everyone in the community, but you’re protected from age-based hikes. This method offers great long-term predictability, which can be a huge relief for your budget over the years.

Issue-Age-Rated

Issue-age-rated plans lock in your premium based on your age when you first buy the policy. So, if you enroll at 65, you’ll get a lower rate than someone who enrolls at 70. The good news is that your premium isn’t supposed to increase just because you get older. However, it’s important to know that your rate can still go up. The insurance company can raise premiums for everyone with that plan due to factors like inflation or overall healthcare cost trends. This method can be a great deal if you buy your plan when you’re younger, as it helps protect you from the steep age-related increases you might see with other pricing structures.

Attained-Age-Rated

Attained-age-rated plans are the most common, and they work just like the name sounds: your premium is based on your current age. These plans typically start with the lowest monthly premiums, which can make them look very appealing when you first enroll at 65. However, your rate will increase as you get older, often on your birthday each year. On top of these age-based increases, your premium can also go up due to inflation. While the initial savings are nice, these plans can become significantly more expensive over the long term. It’s crucial to understand how costs can change before choosing this type of plan.

Don’t Forget to Ask About Discounts

Don’t be shy about asking for a discount—you might be surprised by what’s available. Many insurance companies offer discounts that can help lower your premiums. A common one is a household discount, which you might get if you and your spouse are both enrolled in plans from the same company. Some insurers also offer discounts for setting up automatic payments from your bank account or for being a non-smoker. When you’re comparing plans, always make it a point to ask the agent or company representative about any discounts you might qualify for.

Which Companies Offer Medigap Plans?

Once you’ve decided on a Medigap plan letter, like G or N, your next step is to choose an insurance company. This is a crucial step because while the government standardizes the benefits for each plan letter, the companies that offer them are all different. Medigap plans are sold by private insurance companies, not by Medicare itself. This means that a Plan G from one company has the exact same basic medical benefits as a Plan G from another company.

So, what’s the difference? The price. Monthly premiums for the same exact plan can vary significantly from one company to the next. Beyond cost, companies also differ in their customer service, financial stability, and how they price their plans over time. Some companies are known for low introductory rates that increase sharply later, while others have more stable pricing. That’s why it’s so important to compare your options carefully. You’re not just picking a plan; you’re choosing a company to partner with for your healthcare coverage for years to come.

A Look at Major Medigap Providers

Think of us at The Big 65 as your expert guide rather than an insurance company. We don’t offer Medigap plans ourselves. Instead, we are an independent agency that helps you sort through all the options from the major insurance carriers in your state. Our job is to make this process easier for you. We provide the tools and one-on-one guidance to help you understand the fine print, compare costs, and find the best plan and company for your specific needs and budget. We do the heavy lifting of researching and comparing so you can feel confident in your choice.

Aetna

Aetna is a well-known name in the insurance world, and they are a major player in the Medigap market. They offer a solid range of plans, including the popular Plan G and Plan N. Many people are drawn to Aetna because of their competitive pricing and strong reputation for customer service. When you’re dealing with medical bills and claims, having a company that is responsive and helpful can make a huge difference. If a good balance of reasonable cost and reliable support is important to you, Aetna is definitely a company to have on your comparison list.

Cigna

If you’re focused on finding the lowest possible premium, Cigna might catch your eye. They are often recognized for having some of the most competitive rates, especially for Plan N. However, it’s important to look at the full picture. According to some industry reviews, Cigna has a higher-than-average number of complaints compared to its size. This doesn’t mean you’ll have a bad experience, but it’s a factor to consider. For some, the potential monthly savings is worth it, while others may prefer to pay a bit more for a company with a stronger customer service record.

Mutual of Omaha

Mutual of Omaha is another long-standing, reputable company that many people trust for their Medigap coverage. One of their standout features is the potential for discounts. They often offer a significant household discount if you and your spouse both enroll in a plan, which can lead to substantial savings over time. They provide the most popular plans, like G and N, though their overall selection might be smaller than some competitors. If you’re eligible for a household discount, it’s absolutely worth getting a quote from Mutual of Omaha to see how it stacks up.

AARP/UnitedHealthcare

You’ll almost always see AARP and UnitedHealthcare mentioned together. UnitedHealthcare is the insurer for the AARP-branded Medicare plans. Their biggest strength is the extensive range of Medigap plans they offer, which are available in all 50 states. This wide availability and variety of choices can be a huge plus. However, for some people, having so many options can feel a little overwhelming. The AARP endorsement is a big draw for many, and their nationwide presence makes them a reliable choice no matter where you live.

Blue Cross Blue Shield

Blue Cross Blue Shield (BCBS) is a bit unique. It’s not a single national company but a federation of 34 independent, locally operated companies. This means that the BCBS in your state is different from the one in the next state over. Because of this structure, the plan offerings, pricing, and customer service can vary quite a bit depending on where you live. They are generally a well-regarded option with strong local networks, but you’ll need to research your specific state’s BCBS provider to get an accurate picture of what they offer.

Humana

Humana is another one of the largest and most recognized providers of Medigap plans. They offer several options, including the highly sought-after Plan G and Plan N. Humana is often noted for its focus on customer support and providing helpful resources to its members. Like some other large carriers, their pricing and plan availability can sometimes differ by state, so it’s important to get a quote specific to your area. If you value strong customer service and want a plan from a stable, well-known company, Humana is a solid contender to include in your comparisons.

Related Articles

Frequently Asked Questions

What’s the real difference between Plan G and Plan N in simple terms? Think of it as a trade-off between your monthly bill and what you pay when you see a doctor. With Plan G, you pay a higher monthly premium, but once your annual Part B deductible is met, your medical costs are almost entirely covered. Plan N offers a lower monthly premium, but in exchange, you agree to pay small, predictable copayments for some doctor and ER visits. The other key difference is that Plan G covers Part B excess charges, while Plan N does not.

If all plans with the same letter are identical, should I just pick the cheapest company? While it’s tempting to just go for the lowest price, the company you choose really does matter. The benefits of a Plan G are the same everywhere, but the company’s history of rate increases and its customer service are not. Some companies might offer a low introductory rate that climbs steeply over the years. Choosing a stable, reputable company can save you money and headaches in the long run.

I keep hearing about Plan F. Why isn’t it a main option anymore? You’re right, Plan F was once the most popular plan because it covered everything. However, a federal law changed the rules for anyone who became eligible for Medicare on or after January 1, 2020, making Plan F unavailable to them. For new Medicare members, Plan G has effectively taken its place as the most comprehensive option available. It offers the same robust coverage as Plan F, with the single exception that you pay the annual Part B deductible yourself.

Can I switch my Medigap plan easily if my health changes later on? Switching plans isn’t always a simple process. When you first enroll in Medicare, you have a special open enrollment period where you can buy any Medigap plan without answering health questions. Outside of that window, insurance companies can generally require medical underwriting. This means they can review your health history and potentially charge you a higher premium or even deny coverage. This is why it’s so important to choose a plan that you feel will serve you well for years to come.

Do these Medigap plans help pay for my prescription medications? This is a fantastic question and a common point of confusion. Medigap plans are designed to help cover the costs associated with Original Medicare Parts A and B, which are your hospital and medical insurance. They do not include coverage for prescription drugs. For that, you will need to enroll in a separate Medicare Part D prescription drug plan.

What If You Need Help with Medicare Costs?

Even with the right Medigap plan, the combined costs of premiums and other healthcare expenses can feel like a stretch, especially if you’re on a fixed income. It’s completely normal to be concerned about your budget. The good news is that you don’t have to figure it all out on your own. There are several established government programs designed specifically to help people with limited income and resources pay for their healthcare costs. Taking the time to see if you qualify for one of these programs can make a significant difference in your monthly budget and provide an extra layer of financial security.

These programs can help with everything from paying your monthly Medicare premiums to covering deductibles and coinsurance. While the application process and eligibility requirements can seem a bit complicated at first, the potential savings are well worth the effort. Think of it as one more step in creating a comprehensive healthcare plan that truly works for you, both medically and financially. Below, we’ll walk through some of the key programs that can provide valuable assistance.

Exploring Financial Assistance Programs

If you’re looking for ways to lower your healthcare spending, several federal and state programs are available to help. These programs have specific income and resource limits, which can vary by state and change from year to year. It’s important to look at the requirements for your specific location to see if you might be eligible. Understanding these options can help you access valuable benefits that make your medical care much more affordable, ensuring you can get the care you need without the financial strain.

Medicaid

Medicaid is a joint federal and state program that provides health coverage to millions of Americans, including many seniors with low income. It works differently from Medicare and can help cover costs that Medicare doesn’t, such as long-term care services at home or in a nursing home. Because each state administers its own Medicaid program, the eligibility rules and benefits can vary significantly. If you think you might qualify, your first step should be to check the specific guidelines for your state’s Medicaid agency.

Medicare Savings Programs (MSPs)

Medicare Savings Programs (MSPs) are state-run programs, funded by the federal government, that are designed to help people with limited income pay for their Medicare costs. Depending on your income level, an MSP could help pay for your Part A and Part B premiums, deductibles, and coinsurance. For many people, just having their Part B premium covered provides significant monthly savings. You can learn more about the different types of Medicare Savings Programs and their income requirements on the official Medicare website.

PACE

The Program of All-Inclusive Care for the Elderly, or PACE, is a unique program offered by Medicare and Medicaid. It’s designed to help older adults who need a nursing home level of care to continue living safely in their community. PACE provides a comprehensive package of medical and social services, including primary care, physical therapy, prescription drugs, and even transportation. This coordinated approach helps manage all of your healthcare needs through a single team. You can find more details about how the PACE program works and if it’s available in your area.

Veterans Health Administration (VA) Benefits

If you are a veteran, you may be eligible for healthcare benefits through the U.S. Department of Veterans Affairs (VA). VA health care can work alongside your Medicare coverage, and in some cases, it may reduce your out-of-pocket costs. Eligible veterans can receive a wide range of services, including hospital care, outpatient services, and long-term care. It’s a valuable benefit that you’ve earned through your service. To see if you qualify and to learn more about what’s offered, you can explore the VA health care website.
We survived the earthquake 🌍!

Greetings and may this blog find you in amazing health, with your Medicare insurance coverage🏥working well.

Any issues with your Medicare coverage (and the carrier isn’t helping), or you’d like to shop coverage? Email Gray, Gray@TheBig65.com or book a time on my calendar.

Remember to hang up 📞 on the big illegal call centers ⚠️ that try to force the wrong plans on consumers. Always use an independent broker, like The Big 65. That’s why we’re here.

Quantz and I are exploring Istanbul🕌✨, an ancient city where East meets West. It’s a fascinating mix of Europe and Asia and it’s filled with surprises😲.

Karl surrounded by ancient buildings as he stares up at the deep blue sky.

Like the Grand Bazaar, one of the oldest covered markets in the world, thousands of shops selling spices, food, and clothing. You can get lost in this place if you don’t use Google maps.

A woman with blond hair looking out at the huge Grand Bazaar.

It’s fun to try new things: mulberries, persimmons, even Turkish delight🍬. Of course Q is way more adventurous then I am, but that’s why we have balance in our relationship…

One explorer and one boring insurance dude to keep things on track.

Quantz admiring fruit at the Bazaar.

Istanbul is filled with dogs and cats that roam freely and are fed and housed with public funds.

A whitish cat sitting on a tan moped.

As long as you see a tag in the dog’s ears, or a clipped spot on the cat’s ears, you know they’ve been vaccinated and protected.

Quantz studying a white dog.

On Thursday, as I was walking to meet a friend for coffee, we experienced a 6.2 magnitude earthquake 🌍 that shook for thirteen seconds.

Thousands of people streamed out of every building but there was no major damage, thank goodness😮‍💨!

As Yusuf and I drank Turkish coffee, every member of his family called him to make sure he was OK.

What a great reminder to live every day as if it is your last.

Karl and his friend Yusuf looking at the camera over Turkish coffee.

Keep squeezing the juice out of life and look for ways to help others!

If family or friends need help… referrals are the lifeblood of my business.

If you know someone who might like to receive The Big 65 newsletter, forward this link.

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@TheBig65.com.

Let us know what’s going on and please send pictures :).


Karl Bruns-Kyler
(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in thirty states around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Kentucky
Louisiana
Maryland
Michigan
Minnesota
Missouri
Montana
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Medicare insurance broker Karl Bruns-Kyler of The Big 65 Medicare insurance services company.


Don’t ever pay…immediately ⚠️!

Hello and may this blog find you in amazing health with your Medicare insurance coverage 🏥 working well.

For Medicare questions or concerns, book a time on my calendar or email Gray, Gray@TheBig65.com if you need us.

If you were driving the backroads of Mexico and you came across a cowboy 🤠 leading his cattle🐄 across the road, you’d slow down, right?

A farmer and his cows crossing a dirt road in Mexico.

Consider using the same strategy when it comes to paying Medicare medical bills—proceed with caution⚠️.

One Medicare client received a shocking $50,000 hospital bill😱, but after a few calls, it was corrected to less than $1,000. What a difference😌!

To avoid overpaying, separate the forest from the trees.

Here’s what to do:

A large Montezuma cypress tree.

Review Your Bill Carefully:

  • Never pay the bill  immediately.
  • Request an itemized statement from your healthcare provider.
  • Look for duplicate charges, services you didn’t receive, or any unfamiliar billing codes, called CPT codes.A Mexican woman with a pink hat preparing food on the street.

Compare with Your Insurance Coverage:

  • Cross-check the charges against your Medicare Summary Notice (MSN) or Explanation of Benefits (EOB).
  • Verify that the services are covered and that the charges align with your plan’s benefits.

Karl and Quantz having a meal and looking back at the camera.
Contact Your Healthcare Provider’s Billing Department:

  • If something doesn’t look right, call the billing department to discuss the charges.
  • Request a review and ask them to resubmit the claim to Medicare or to your insurance plan if there are errors.

A brown dog with a white flower on its back sitting in sand.

Remember, slowing down to verify your medical bills can save you thousands of dollars. Here’s an article from Medicare. This problem occurs with Medicare Supplements, Medicare Advantage Plans, and Part D Drug Plans. Beware!

If you have questions about Medicare or need assistance navigating your coverage, we are here if you need us.

Quantz flanked by a gentleman gliding in the sky.

Keep squeezing the juice out of life and look for ways to help others!

If family or friends need help… referrals are the lifeblood of my business.

If you know someone who might like to receive The Big 65 newsletter, forward this link.

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@TheBig65.com.

Let us know what’s going on and please send pictures :).


Karl Bruns-Kyler
(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in thirty states around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Kentucky
Louisiana
Maryland
Michigan
Minnesota
Missouri
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Karl Bruns-Kyler of The Big 65, the nationally recognized Medicare insurance expert.

Here’s what’s different for next year🤔!

Greetings and may this blog find you in amazing health 💪 with your Medicare insurance coverage 🏥 working properly. Are you avoiding all call center noise☠️⚠️?

Plato says 32 inches of snow is even better than the previous 12 and he wants more.

Plato the dog playing in the Colorado snow.

For more Medicare questions, quotes, or quandaries, email Gray@TheBig65.com or book a time on my calendar and we’ll get it sorted.

I’m pleased to report our Air Force son is home for a few weeks before he redeploys to Italy. Plato is happy to have him around.

Karl's air force son being welcomed home by Plato.

Quantz is happy to have her boy home as well. Of course, she’s spoiling him and they are having as much fun as possible. They even took an Italian cooking class.

Quantz and Nick taking an Italian cooking class in the kitchen.

Me, I’m keeping my cool and trying hard to keep my head above water during this busy season.

Karl sitting in a cold plunge tub as he looks at Plato in his back yard surrounded by snow.

Here are a few of the changes coming into play for 2026:

  • The annual deductible for Part B will rise to $283, up from $240 in 2024.
  • The standard monthly premium for Medicare Part B will be $202.90. If you’re receiving Social Security benefits, this amount will be automatically deducted from your monthly payment.
  • Starting in 2025, there will be an annual $2,100 cap on out-of-pocket spending for prescription drugs under Part D. Once beneficiaries reach this limit, they won’t have to pay additional costs for covered medications for the remainder of the year.

At least that’s something to celebrate, right Jean?

A nice lady sitting in front of her birthday cake.

It’ll be interesting to see how the new administration deals with Medicare and Social Security, but no news yet.

As we get to the holidays, I hope you’re taking time out to enjoy time with your family. They sure grow up fast.

A man with a blue shirt enjoying a drink from a big glass.

Keep squeezing the juice out of life and look for ways to help others!

If family or friends need help… referrals are the lifeblood of my business.

If you know someone who might like to receive The Big 65 newsletter, forward this link.

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@theBig65.com.

Let us know what’s going on and please send pictures :).

Karl Bruns-Kyler
(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in thirty states around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Kentucky
Louisiana
Maryland
Michigan
Minnesota
Missouri
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Karl Bruns-Kyler Medicare Insurance Broker.

Get off your high horse!

Greetings and may this blog post find you in great health 💪 with your Medicare coverage 🏥 working properly.

Are you having any issues with your coverage? If so, reach out and book a time on my calendar. Anyone on an Advantage plan has till the end of March to make a change if they are unhappy!

OK, the sky’s not falling, but I am on my high horse, watching out for scams. Despite writing about this last week, we almost got burned🔥.

Karl sitting on his high horse.

My wife Q received this email invoice and asked me if we should pay😱! It’s always worth a second look before you pay a bill and this one was completely bogus.

Bogus invoice from PayPal.

This week, we need to revisit Medical Billing. Now don’t fall asleep 😪. If we don’t pay attention to these common billing mistakes, it could cost us money💰.

Salt flats in the Bolivian Andes.

According to Becker’s Hospital CFO Report, 4 out of 5 medical bills contain at least one minor error.

Quantz traveling.

Not all of these errors result in higher bills, but many do. If there is an error in your bill, according to Medicare, here are a few of things you can do.

Back in Highlands Ranch.

→ Get a detailed bill resent by the provider and check it to make sure the service you were billed for was actually the service you received.

Plato in Highlands Ranch.

→ Ask the doctor for a copy of your medical records and compare this to the bill.

Rembrandt paining.

→ Look up the medical billing codes online. Compare them to your bill. If they don’t match what you got, contact your provider’s billing department.

Medicare insurance broker Karl Bruns-Kyler of The Big 65.

→ Confirm the bill was actually sent to your insurance company. Billing departments sometimes send bills to the consumer instead of sending them to the insurance company.

Museum in Amsterdam Karl
→ Call the billing department and have them submit the bill to the insurance company so that it is processed correctly.

263 sign in window.

→ If you are stuck with an expensive bill, make sure they are charging a fair price and not overcharging you ($200 aspirin). Consider checking FairHealth to get a sense of fair market prices and negotiate from there.

View of Amsterdamn.

→ You can also ask for help from a Patient Assistance program in your state.  Here is a link.

Karl standing in a church.

→ One final tip: “If you’re being admitted to a hospital and asked to sign a document of financial responsibility, write in that you agree only if your care is in network, says Elisabeth Rosenthal, M.D., author of “An American Sickness.” See Consumer Reports.Plaque of the Dutch support of the American Revolution.

In the meantime, keep squeezing the juice out of life and look for ways to help others!

Medicare questions or problems?

Book a time on my calendar or email Gray, Gray@theBig65.com.

If family or friends need help… referrals are the lifeblood of my business.

Let us know what’s going on and please send pictures :).


Karl Bruns-Kyler
(877) 850-0211
Book a time on my calendar here
Happy with my Service? Click Here to Leave a Review.


Karl Bruns-Kyler is a Medicare insurance broker and independent Medicare agent licensed to help Medicare recipients in thirty states around the country, including:

Alabama
Arizona
Arkansas
California
Colorado
Connecticut
Florida
Georgia
Idaho
Indiana
Iowa
Kansas
Louisiana
Maryland
Michigan
Minnesota
Missouri
Nevada
New Hampshire
New Jersey
New York
North Carolina
Ohio
Oklahoma
Pennsylvania
South Carolina
Tennessee
Texas
Virginia
Washington
Wisconsin

The Big 65 Medicare Insurance Services does not offer every plan available in your area. Currently, we represent 10 organizations that offer 50 products in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.

Logo for The Big 65 Medicare Insurance Services company.